

I’ve been an economics professor for almost 30 years, but I don’t think I’ve ever before seen anything like the table below. I knew that claims that “58% of Americans can’t afford a $1,000 car repair” were laughable clickbait. I knew that — measured by income — the middle class is disappearing… by becoming upper-middle class. But only recently did I start to fully appreciate the chasm between populist pessimism and actual data on Americans’ net worth. From the 2022 Survey of Consumer Finances:
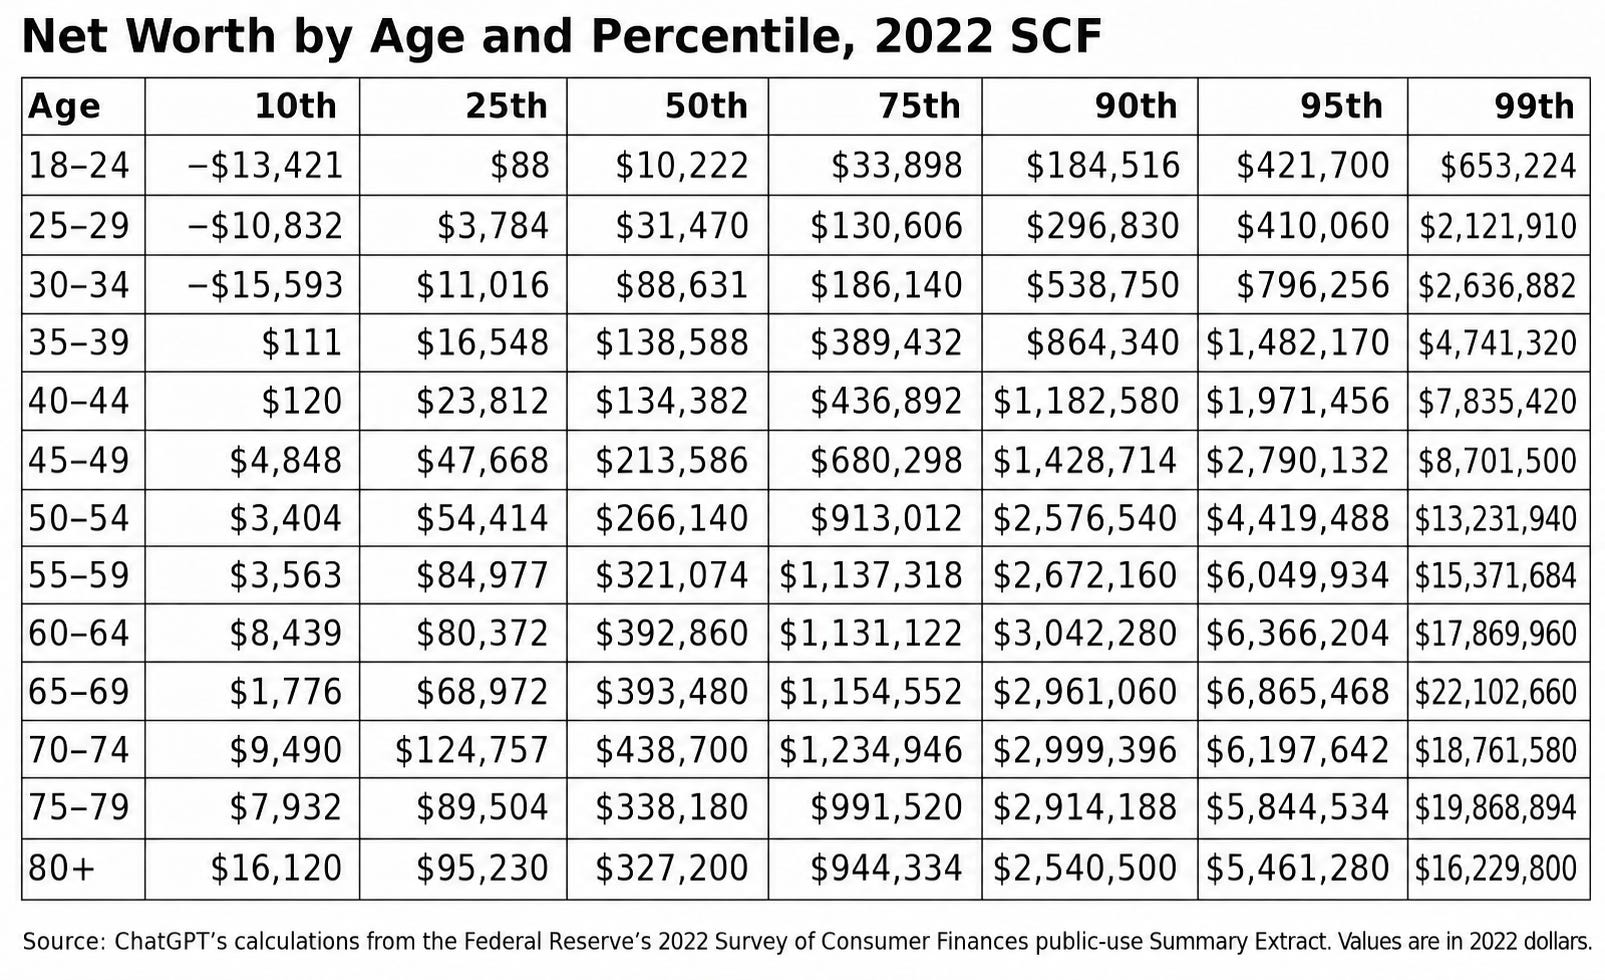
I had ChatGPT work with the actual data, which it then cross-checked against other published estimates. The SCF net worth data is ultimately derived from very finely-grained self-reports, designed to remind respondents to put a dollar value on each and every one of their notable assets and liabilities.
Main reflections:
Economists have long known that inequality is relatively low for consumption, medium for income, and high for wealth. What they rarely emphasize, however, is how much wealth depends on age. The richest Americans aged 65-69 are worth about 30x as much as the richest Americans aged 18-24.
Net worth is very high in absolute terms. The median is over six figures by the mid-30s. Americans at the 75th percentile are millionaires by their mid-50s. Americans at the 90th percentile are millionaires by around 40. Claims about middle-class, middle-aged Americans who “can’t afford” eggs or gas or beef are nonsense.
The most sensible argument for worrying about trade deficits is that we’re “living beyond our means.” Trade deficits represent borrowing, and we can’t keep borrowing forever. But given Americans’ extraordinary net worth, the most sensible argument for worrying is still senseless. After 50 years of unbroken trade deficits, we’re wealthier than ever.
Americans of staggering net wealth are all around us. If you walk around an American mall on a weekend, you probably cross paths with several decamillionaires. But except for being older, you probably couldn’t pick them out of a crowd. Even their cars rarely scream extreme wealth.
Whatever your complaints about American capitalism, you’ve got to admit that a large share of Americans use the system to become staggeringly wealthy by the time they retire. Not 1% or 5%, but 25%.
Americans with low or negative net wealth are also all around us. But who ever thought otherwise? In my 20s, I had very low net worth, and so did all my friends. And that fact contains a lesson: Almost all low-wealth Americans are young. If you have a regular job and age a couple decades, you’re rarely poor anymore.
If you’re old and your wealth is still low, your financial situation is basically hopeless. You can still be happy, but it would take a miracle (like winning the lottery) for your finances to dramatically improve. Every other American, however, is already rich, or could become rich with durably cautious budgeting. The math behind “Skip a $5 coffee every day from the age of 18, invest the savings in the stock market, and you’ll have hundreds of thousands of extra inflation-adjusted dollars when you retire” is sound.
Earning regular high income is the easiest way to end up with high wealth. But it’s neither necessary nor sufficient. A high-skilled worker who blows his whole paycheck week after week ends up with a net worth of roughly zero. A Costco cashier with a high savings rate ends up a millionaire. That’s not just a freak anecdote. It’s math.
Wealth peaks around age 70, roughly what you’d expect given the permanent income hypothesis. What’s surprising is how slowly wealth declines from this peak! Americans over 80 are still loaded, generally having higher net worth than they had 30 years earlier. And despite this wealth, Social Security checks keep rolling in.
Given their current net wealth, a solid majority of Americans can comfortably retire without Social Security. The federal government could cut them off completely and they’d still do fine. The best rationale for the status quo is paternalism, but most Americans are well-prepared for their futures even ignoring Social Security.
What’s a “solid majority”? Median net worth peaks at about $400k, which is more than enough to live the last third of your life in comfort. I wouldn’t say the same about the 25th percentile, though. My ballpark: 60% of Americans could comfortably get by with zero Social Security even though they were counting on it.
Granted, the median American has over half of his net worth in home equity. So without Social Security, people would commonly downsize or use negative mortgages to fund their living expenses. My line in the sand: That is “doing fine.” If you’re living small because you’re determined to bequeath an unmortgaged house to your kids, that’s on you.
In the absence of Social Security, Americans would obviously save more. So in the long run, this table actually overstates the share of unfortunate and improvident retirees.
The word “gerontocracy” is becoming more common, but not nearly common enough. The U.S. is obsessed with ensuring the financial security of elderly Americans who already have more wealth than they know what to do with.
“More wealth than they know what to do with.” Part of the reason my net worth is so high is that I don’t really want to do many expensive things. I’ve built up strong habits of frugality, and spending money fruitfully is aggravating work. Looking at the table, I suspect that many wealthy people are in the same position.
If you look at the table and think, “Wow, there are so many wealthy people available to fund redistribution,” you’re not wrong. But gerontocratic policies are one of the main reasons why there’s so much inequality in the first place.
Worried that if you means-test Social Security, you’ll reduce support for the whole system? We should be so lucky. Our current system wastes trillions of taxpayer dollars based on paranoid fears that some elderly American will end up eating cat food. This dysfunctional system can, should, and must be deeply undermined.
If you’re still complaining about your economic suffering when your net worth is several hundred thousand dollars, your problem is not economic, but psychological. You’re rich, but neurotic. Once you accept this ugly realization, you can start on the hard but rewarding work of learning to appreciate your awesome good fortune.
What’s the most negative possible take on American net worth numbers? Probably, “10 percent of Americans are obscenely rich, and most don’t make more than a token effort to share their good fortune with others.”
What’s the most positive possible take on American net worth numbers? Probably: “25% are unbelievably rich, another 35% are pretty rich, and almost everyone in the remaining 40% has — or at least once had — the opportunity to join them via steady work and savings.”
“…but most Americans are well-prepared for their futures even ignoring Social Security.”
Grrrrr..
I’m with you on *so* much of what you wrote here, but this claim is whack. Bryan is just awful on the math here, and deserves to be taken to the woodshed.
The idea that a median couple with $400K (mostly in home equity) total wealth and no Social Security is well prepared at 65 for a retirement that could last 30 years is just a failure of Bryan to do basic math.
A reverse mortgage rather than selling the house and moving into a cheaper rental shows even less basic math common sense, because it means home overconsumption and even less cash to pay for all other life expenses.
Even if we went beyond the 4% rule and used a 5% spending rate - and assumed said median household knew optimal portfolio allocation - you really want to claim that the average couple at retirement is “well-prepared” living on $20K per year?!?
And it would be much, much less than $20K if based on a reverse mortgage.
And all of the above is separate from the fact that the only reason Bryan can make the sketchy claim he does about “most” is because of government-provided Medicare, which is the real program bankrupting the country that is in far, far worse shape than Social Security.
I don’t claim to have all the answers, and I agree with Bryan on so much else here, but this claim about “most” being fine if Social Security vanished tomorrow is just… whack awful math.
[Addendum: ChatGPT tells me that a reverse mortgage on a $400K house would generate only about $12,000 annually in real income for a 65 year old couple entering into such a contract. (Yes in reality not all of the assets are home equity, so median reality would be a little better than what the $12K suggests. But the point stands.) Even without a mortgage to pay, the idea that said median Americans are “well-prepared for their futures even ignoring Social Security” don’t hunt.]
Agree with everything you said, but I always have felt the major missing component here is the value of a year-of-life.
This is where the young are infinitely more wealthy than the old. You can do the math around a set of discounted QALYs to actually calculate this or you could just intuitively think about it - how much of their "net worth" would a 70 year old offer to be 20 again? This becomes particularly salient if you think about the longevity advances we are about to see. Any rational 70 year old deca-millionaire would give up almost every dollar to be a 20 year old again in 2026.